 The Care Compass®
Money After Losing a Spouse: What's Actually Different, and Where to Start
The short answer
When a husband, wife or civil partner dies, you may be able to inherit extra State Pension. If you were under State Pension age when they died, you may be able to claim Bereavement Support Payment: claim within 3 months to get the full amount, though a later claim (usually up to 21 months) can still pay a reduced amount. You may get a 25% Council Tax discount if you’re now the only adult in the home who counts for Council Tax. Debts in their sole name are normally paid from their estate, not your own money, unless the debt was joint, you guaranteed it, or another legal responsibility applies.
There's already good, detailed guidance on this site for what to do with money and paperwork after any death — our first-days checklist covers pensions, probate, and tracing old policies in full. This page is different. It's specifically about what changes when the person who died was your husband, wife, or civil partner — the things that are genuinely different when it's your other half, not a parent or relative.
If you’re reading this tonight
- Don’t drive their car, or a car insured in their name, until you’ve checked you’re covered.
- Don’t pay a debt in their name only from your own money until you’ve checked whether you’re legally responsible.
- Put letters and important documents together somewhere safe.
- Tomorrow or soon after, start with benefit changes and anything with a claim deadline.
One step that saves a lot of phone calls: Tell Us Once
When you register the death, ask the registrar about Tell Us Once. It lets you tell many government services in one go, such as HMRC, the DWP (including State Pension and benefits), the DVLA, the Passport Office and the local council, instead of contacting each one yourself.
It’s available if your husband, wife or civil partner lived in England, Scotland or Wales. In Northern Ireland, use the Bereavement Service instead (see nidirect).
It doesn’t cover banks, energy suppliers, insurers or private pensions, so you’ll still need to contact those. Our first-days checklist has the full list. Tell Us Once on GOV.UK
Your joint bank account will usually stay available
In England, Wales and Northern Ireland, a joint account will usually remain available to the surviving account holder and normally passes without probate. In Scotland, the account may remain usable, but the money does not automatically become the survivor’s. Ownership depends on who paid money into it and the will or intestacy rules.
Tell the bank’s bereavement team and ask how it will treat the account, particularly if you live in Scotland.
One genuinely valuable, under-known thing: ISAs can't be held jointly, but as a surviving spouse or civil partner you're entitled to an Additional Permitted Subscription (APS) — you can shelter an amount equal to their ISA's value into your own ISA, tax-free, on top of your normal annual ISA allowance. Ask the ISA provider about claiming it, and which valuation applies (it can be the value at the date of death or when their ISA is closed).
Bereavement Support Payment
If you were under State Pension age when your partner died, check whether you qualify for Bereavement Support Payment. It can cover spouses and civil partners, and some cohabiting partners who were pregnant or responsible for a child. Claim within 3 months for the full amount; a later claim may still be possible, usually up to 21 months, but may pay less. Our full guide to financial help after a death covers the rates and how to claim.
Your benefits may change, in either direction
If you or your spouse received means-tested benefits like Universal Credit or Pension Credit, these are worked out on your household, not just one person. Becoming a single-person household changes the calculation — sometimes it goes down, sometimes it actually goes up, since some elements are calculated per person.
Action: report the change of circumstances straight away rather than waiting until things settle. Benefit backdating isn't guaranteed, so a delay can genuinely cost you money either way.
Council Tax: the 25% single-occupancy discount
In England, Scotland and Wales, once you're the only adult living in the property, you're entitled to a 25% discount on Council Tax. (Northern Ireland has domestic rates instead of Council Tax; ask Land & Property Services what help is available.) This is not applied automatically — you need to apply to your council directly, and it isn't backdated indefinitely, so it's worth doing sooner rather than later.
Life insurance and mortgage protection
If your spouse had a life insurance policy or mortgage protection insurance, contact the insurer directly with the death certificate and policy details. If the policy was written in trust, or set up to pay you directly, it can often be paid without waiting for probate. Ask the insurer how it was arranged. Death-in-service cover usually comes only from the employer they worked for when they died, so start there. Old pensions from previous jobs are covered further down, and our first-days checklist explains how to trace old policies.
Your State Pension may go up
This is one of the most overlooked entitlements for widowed people. Depending on your ages and their National Insurance record, you may be able to get extra State Pension based on your husband, wife or civil partner’s contributions, on top of your own.
The rules depend on whether you reached State Pension age before or after 6 April 2016. Under the older system you may be able to inherit part of their State Pension, including Additional State Pension (sometimes called SERPS). Under the new State Pension you may be able to inherit an extra payment on top of your own. If they reached State Pension age before 6 April 2016 and had put off claiming, you may also be able to inherit some or all of the extra State Pension or lump sum they built up.
Two things to know. You generally need to be over State Pension age to receive these extra payments. And if you remarry or form a new civil partnership before you reach State Pension age, you usually lose the right to inherit.
Action: phone the Pension Service and ask them to check what you can claim from your spouse’s record. Don’t assume it’s been worked out automatically.
Their workplace and private pensions
Many workplace pensions pay a survivor’s or dependant’s pension to a husband, wife or civil partner, often for life. Personal pensions and pension pots may pay out a lump sum or let you take over the pot. What you get depends entirely on the scheme, so each one needs contacting.
Action: contact every pension scheme your spouse belonged to, including old ones from previous jobs. If you can’t find them, the free government Pension Tracing Service can help. Ask each scheme what it pays to a surviving spouse and whether any tax is due.
If you were caring for them
If you were getting Carer’s Allowance for looking after your spouse, it doesn’t stop straight away. It usually carries on for up to eight weeks after their death. If you get Universal Credit with a carer element, that also continues for a short time before your claim is recalculated.
It’s worth knowing this so an unexpected payment doesn’t worry you, and so you can plan for when it ends. If caring was your main role, the change can affect which benefits you can claim next, so it’s worth a benefits check (Citizens Advice and Age UK both offer these free).
Tax: what changes for you
If you and your spouse were using Marriage Allowance or Married Couple’s Allowance, these change after a death, and your tax code may need updating. If your income now includes a survivor’s pension, tax may not be taken correctly at first.
Action: once things settle, check your tax code with HMRC, especially if you start receiving a new pension. It’s much easier to fix early than to sort out a bill later.
Inheritance tax: the allowances that pass to you
Anything your spouse leaves to you is normally free of inheritance tax. That’s the spouse exemption.
The part many people don’t know: if your spouse didn’t use their own tax-free allowances (because everything passed to you), the unused share can usually be transferred to you and added to your own. That can make a very large difference to your family later, when your own estate is dealt with. It isn’t automatic. Your executors will need to claim it, using records from your spouse’s estate.
Action: keep copies of your spouse’s will, the probate paperwork and a note of what their estate was worth. Store them with your own will so nobody has to hunt for them later.
From 6 April 2027, most unused pension funds and pension death benefits will count towards a person’s estate for inheritance tax. Pensions left to a spouse or civil partner will still be exempt, but it’s a good reason to check who you’ve named on your own pension nomination forms now that your circumstances have changed.
Their debts are not automatically yours
This frightens a lot of people, so it’s worth saying clearly: you are not responsible for debts that were in your spouse’s name only. Those are paid from their estate, if there’s enough money in it. If there isn’t, the debt is usually written off.
The exceptions are debts in joint names (such as a joint loan, joint overdraft or joint mortgage), and any debt where you signed as a guarantor. Those can become your responsibility.
Action: don’t pay anything from your own money just because a letter arrives addressed to your spouse. Tell the lender about the death, ask whether the debt was joint, and if you’re unsure, get free debt advice from StepChange or Citizens Advice before paying.
The car, the home and the bills
The car: if the policy was in their name, do not assume that named-driver cover continues. Contact the insurer before anyone drives; insurers may end, transfer or temporarily continue the policy. If the policy is in your name, tell the insurer about the change. If they were the registered keeper, tell DVLA and tax the vehicle in the new keeper’s name before using it on a public road.
The home: whether a jointly owned home passes to you automatically depends on how the ownership was set up (in England and Wales, for example, as ‘joint tenants’ or ‘tenants in common’), so check the deeds or ask a solicitor. If it was in their name only, it goes through their will or estate. If you rent, a joint tenancy normally continues in your name. If the tenancy was only in their name, ask your landlord or a housing adviser about your right to take it over before assuming it will transfer. Tell your landlord or housing association, and your mortgage lender if you have one.
Bills: energy, water, phone and broadband accounts in their name need moving into yours. The government’s Tell Us Once service (offered when you register the death, if they lived in England, Scotland or Wales; in Northern Ireland, use the Bereavement Service instead) can tell many government departments for you in one go, including HMRC, the DWP, the DVLA and the council.
Be wary of anyone who gets in touch
Sadly, people who have recently lost a partner are targeted by scams, including fake debt letters, cold calls about investments and people offering to “help” with the estate for a fee. Banks and government departments will never ask you to move money to keep it safe.
It’s also wise to avoid making big, hard-to-reverse money decisions in the first months, such as selling the house, moving savings or lending money to family. There’s rarely a rush, and grief can make everything feel more urgent than it is.
Finding local support near you
Money is only part of this. Whether you're the one who's been widowed, or a family member helping out, our local support finder looks up which council covers a postcode and points you straight to the right local service — carer support, dementia groups, adult social care, help at home, NHS services, money and benefits advice, or bereavement support.
Available now
With You Afterwards
A printed, writable booklet to guide you through the practical steps after losing someone, at your own pace, with checklists to tick off and space to keep track of who you’ve told. 44 pages, £14.99 including UK postage.
There are a lot of people to tell after losing someone. With You Afterwards takes you through it gently, with space to tick off each one as you go.
For yourself £14.99
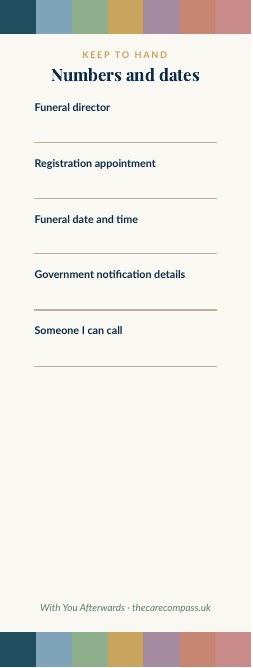
The booklet, with a bookmark inside for jotting down key numbers and dates.
Order for yourself A5 booklet, 44 pages
For someone else £14.99
A practical way to be there when you can’t be there in person. The booklet, bookmark and a ‘Thinking of you’ card with your message, posted straight to them.
Write your message & send Card with your message
Write your message on the next page and see how it looks first. We print it neatly inside the card.
UK postage included · posted within 3 working days
Secure checkout · No account or sign-up needed
Looking for local support near you? Find the right local or national service for your postcode →
A word from The Care Compass
Most of this can be worked through gradually, at your own pace. The things not to leave are: making sure nobody drives without insurance, reporting benefit changes, claiming Bereavement Support Payment (3 months for the full amount), and checking whether any insurance or pension claim has a deadline. The Council Tax discount is worth applying for soon too.
Common Questions
Does a joint bank account get frozen when a spouse dies?
In England, Wales and Northern Ireland, usually not: the account normally remains available to the surviving holder. In Scotland, the account may remain usable, but ownership of the money must be worked out separately.
What is the ISA Additional Permitted Subscription?
An extra ISA allowance equal to your late spouse's ISA value, on top of your normal annual allowance, tax-free.
Do I get a Council Tax discount for living alone now?
In England, Scotland and Wales, usually yes: a 25% single-occupancy discount — but you need to apply for it, it isn't automatic. In Northern Ireland, ask Land & Property Services about help with rates.
Will my benefits change?
Likely, in either direction. Report the change straight away rather than waiting.
Can I get extra State Pension after my husband or wife dies?
Often, yes. Depending on your ages and their National Insurance record, you may be able to inherit extra State Pension. The rules depend on whether you reached State Pension age before or after 6 April 2016. Ask the Pension Service to check.
Am I responsible for my spouse’s debts?
Not for debts in their name only. Those are paid from their estate, and written off if there isn’t enough. Joint debts, or debts you guaranteed, can become yours.
Does Carer’s Allowance stop when the person I care for dies?
Not straight away. It usually continues for up to eight weeks after the death.
Do I have to pay inheritance tax on what my spouse leaves me?
Normally no. Anything left to a husband, wife or civil partner is usually exempt, and their unused tax-free allowance can usually be passed to you for later.
This article is for guidance only and does not constitute financial advice. Always confirm current rules with your bank, council, solicitor or a regulated financial adviser.
You don’t have to navigate it alone.
Was this helpful to read?
Sorry it didn’t quite help. What was missing?
Thank you — that’s really useful to know.
Help another family find us
A short Google review helps families searching late at night find calm, free guidance when they need it.
Leave a Google review →Didn’t find what you needed?
This page can’t cover every situation. If something’s still unclear, send us a quick message and we’ll do our best to help or point you in the right direction. For support right now, Admiral Nurses (via Dementia UK) offer free specialist advice by phone, and Marie Curie has a free support line for anyone affected by a terminal illness.